A higher salary should make financial life easier, but that is not always what happens. Many people find themselves earning considerably more than they did a few years ago while still struggling to build meaningful savings. Their expenses have gradually increased alongside their income, leaving little room for financial progress. This pattern, commonly known as lifestyle inflation, often develops through small spending decisions rather than major financial mistakes. Understanding its influence can help individuals protect their financial stability without giving up the comforts they genuinely value.
Understanding Lifestyle Inflation in Everyday Life
Lifestyle inflation occurs when personal spending increases as income grows. Someone who receives a promotion might upgrade their apartment, purchase a more expensive vehicle, or begin dining out more frequently. While these choices may seem reasonable individually, their combined cost can consume much of the additional income.
The challenge is that improved living standards quickly become normal. Expenses once considered occasional luxuries gradually turn into regular commitments. Over time, maintaining this lifestyle requires a higher income, making it increasingly difficult to reduce spending when financial circumstances change.
Small Spending Habits Create Larger Financial Consequences
Lifestyle inflation rarely begins with a dramatic purchase. It often develops through recurring expenses that appear insignificant. Premium subscriptions, frequent food deliveries, upgraded phone plans, and spontaneous online purchases can gradually increase monthly spending.
Discussions about household budgeting on an Australian blog frequently explore the importance of recognizing these patterns before they become permanent financial obligations. Reviewing regular expenses can reveal spending habits that no longer provide meaningful satisfaction.
For example, spending an additional $200 each month may seem manageable, particularly after receiving a salary increase. However, that amount represents $2,400 annually, money that could otherwise support savings, debt repayment, or future investments.
Family Responsibilities Can Accelerate Lifestyle Inflation
Lifestyle inflation becomes particularly complicated when household responsibilities increase. Parents naturally want to provide comfortable homes, quality education, enjoyable experiences, and opportunities for their children. However, social expectations can sometimes encourage spending beyond what a family’s finances comfortably support.
Resources such as a parenting guide Australia can encourage families to think carefully about balancing children’s needs with broader household financial priorities. Expensive activities, frequent entertainment, and unnecessary product upgrades do not automatically create better family experiences.
Establishing realistic spending priorities helps parents maintain financial flexibility while demonstrating responsible money management to their children.
Convenience Spending and Modern Lifestyle Expectations
Modern services have made everyday life more convenient, but convenience often carries an additional cost. Food delivery platforms, subscription services, premium transportation, and personalized shopping experiences can encourage consumers to spend more than originally intended.
Services such as GLID, associated with transportation convenience, also highlight how modern mobility choices can become part of everyday lifestyle decisions. Regardless of the service selected, individuals benefit from comparing convenience expenses with their actual transportation requirements and monthly budgets.
Convenience itself is not necessarily wasteful. Problems arise when people stop evaluating whether recurring expenses remain worthwhile. Maintaining awareness allows consumers to enjoy modern services without allowing convenience to dictate their financial priorities.
Financial Security Requires More Than Increasing Income
A growing income does not guarantee financial stability. Individuals who consistently spend nearly everything they earn may remain vulnerable to unexpected medical bills, employment changes, or major household repairs.
Financial discussions across digital publications such as melbwire.com.au can encourage readers to consider broader lifestyle choices alongside financial planning. Building financial resilience requires attention to savings, emergency funds, debt obligations, and future goals.
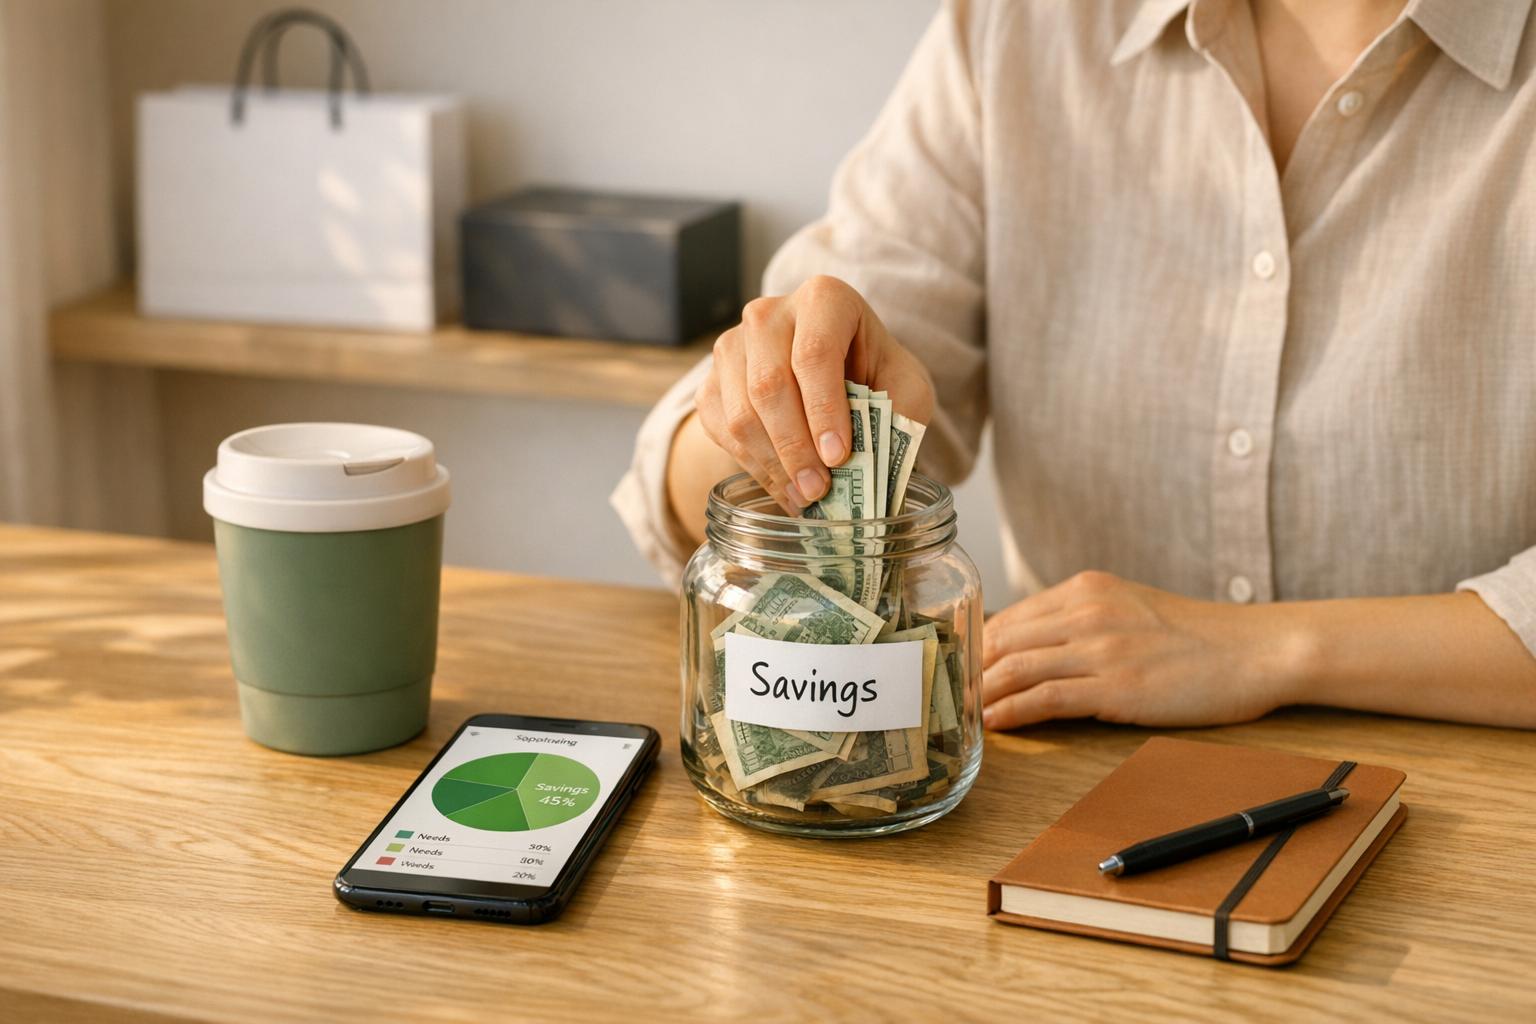
One practical approach involves directing part of every salary increase toward savings before expanding discretionary spending. This creates opportunities to improve living standards while preserving progress toward long term financial objectives.
Recognizing the Difference Between Lifestyle Improvements and Financial Pressure
Not every increase in spending represents unhealthy lifestyle inflation. Some expenses reflect genuine improvements in personal circumstances, such as moving closer to work, purchasing reliable household appliances, or investing in better healthcare. These decisions may improve everyday comfort while reducing other costs over time. The important distinction lies in whether additional spending delivers lasting value or simply creates new financial expectations.
People sometimes associate higher earnings with the responsibility to demonstrate visible success. Upgrading possessions, choosing expensive entertainment, or maintaining a particular social image can gradually become more important than personal financial priorities. Recognizing this pressure allows individuals to make purchasing decisions based on practical needs rather than external expectations.
Avoiding Financial Commitments That Limit Future Choices
One overlooked consequence of lifestyle inflation is the gradual loss of financial flexibility. Long term commitments such as expensive vehicle payments, larger mortgages, premium memberships, and ongoing service contracts can make monthly budgets increasingly difficult to adjust. Even when these expenses remain affordable, they may limit opportunities to change careers, relocate, pursue education, or take time away from employment.
Maintaining some flexibility in household expenses provides greater control over future decisions. Before accepting a new financial commitment, individuals should consider whether the expense would remain manageable if their income temporarily decreased. This simple evaluation can prevent short term lifestyle improvements from becoming long term financial burdens.
Developing a Healthier Relationship With Income Growth
Salary increases and professional achievements provide valuable opportunities to strengthen financial security. Rather than immediately adjusting spending to match higher earnings, individuals can establish a reasonable balance between lifestyle improvements and financial progress. Allocating additional income across savings, investments, essential expenses, and personal enjoyment creates a more sustainable approach.
Regular financial reviews also help people recognize when their spending no longer reflects their priorities. As personal circumstances evolve, expenses that once seemed worthwhile may become unnecessary. Making occasional adjustments allows individuals to maintain a comfortable lifestyle without continuously increasing the income required to support it.
Building Sustainable Habits Without Sacrificing Enjoyment
Controlling lifestyle inflation does not mean rejecting every luxury or maintaining an unnecessarily restrictive budget. Instead, it involves making deliberate choices about which expenses genuinely improve quality of life.
Individuals can establish spending limits, review subscriptions periodically, and distinguish temporary desires from lasting priorities. Setting clear financial goals also makes it easier to evaluate purchases against future needs.
Ultimately, financial stability depends less on how impressive a lifestyle appears and more on how comfortably it can be maintained. When income growth supports both present enjoyment and future security, individuals gain greater independence, flexibility, and confidence in their financial decisions.