Money influences nearly every part of daily life, yet many financial decisions receive surprisingly little attention. People carefully research expensive purchases but often overlook smaller choices that gradually affect their financial stability. Monthly subscriptions, transportation expenses, shopping habits, and lifestyle preferences may appear insignificant individually, but their combined impact can be substantial. Understanding personal finances requires more than earning enough to cover immediate expenses. It involves recognizing spending patterns, evaluating priorities, and considering the long term consequences of everyday choices. Developing financial awareness can help individuals make decisions that support both present comfort and future security.
The Real Cost of Everyday Convenience
Convenience has become an important part of modern living. Food delivery services, online shopping platforms, subscription memberships, and digital payment systems make daily activities easier. However, the financial cost of convenience is not always immediately obvious. Small service charges, delivery fees, and recurring payments can accumulate without attracting much attention.
Consider someone who regularly orders meals instead of preparing food at home. Each purchase may seem affordable, particularly when compared with the effort required to cook. Over several months, however, the total expense could represent a meaningful portion of their income. Evaluating convenience spending does not mean eliminating enjoyable services. Instead, it involves understanding whether the benefits justify the costs and identifying opportunities to make more balanced choices.
Choosing Transportation Options With Financial Awareness
Transportation is another area where routine decisions can influence household expenses. Many people choose their preferred travel methods based on familiarity rather than comparing available alternatives. Fuel costs, parking charges, vehicle maintenance, insurance, and public transportation fares all contribute to the overall cost of mobility.
Digital resources such as pinksahelimetrocard.com may attract readers interested in transportation cards and related travel information. Before relying on any transportation resource, individuals should verify current fares, eligibility requirements, and official service details. Comparing commuting expenses can help people determine whether public transportation, shared travel, or private vehicles offer better value for their circumstances. A thoughtful transportation budget can also reveal savings opportunities that might otherwise remain unnoticed.
Recognizing the Difference Between Affordability and Value
A product being affordable does not necessarily make it a worthwhile purchase. Similarly, an expensive item is not automatically a poor financial decision. The relationship between price, quality, durability, and usefulness determines whether something offers genuine value.
For example, purchasing inexpensive furniture that requires frequent replacement may eventually cost more than investing in a durable alternative. The same principle applies to clothing, electronics, appliances, and household equipment. Evaluating purchases based on expected lifespan and practical benefits encourages more responsible spending. Consumers who consider long term value are often better positioned to avoid unnecessary replacements and make purchases that align with their actual needs.
Reviewing Lifestyle Spending Before It Becomes Routine
Lifestyle expenses can gradually increase as income grows or personal circumstances change. Dining out more frequently, upgrading digital devices, or choosing premium services may become normal without deliberate consideration. This gradual expansion of spending can reduce the amount available for savings and future investments.
Lifestyle discussions found on platforms such as GLID Blog can provide inspiration for exploring different routines, interests, and everyday experiences. However, financial priorities should remain personal rather than being shaped entirely by external trends. Reviewing discretionary expenses periodically allows individuals to identify which activities genuinely improve their quality of life. This approach supports enjoyable living while preventing unnecessary financial pressure from becoming part of everyday routines.
Considering the Financial Impact of Housing Choices
Housing decisions are among the most significant financial commitments many people make. Renting, purchasing property, relocating, or renovating a home can affect household finances for years. Unfortunately, emotional preferences sometimes overshadow practical considerations during these decisions.
A larger property may offer additional comfort, but it can also introduce higher utility bills, maintenance expenses, insurance costs, and ongoing responsibilities. Similarly, moving closer to employment opportunities might involve higher housing costs while reducing commuting expenses. Evaluating these factors together provides a more realistic understanding of affordability. Housing decisions should reflect both current financial capacity and potential changes in employment, family needs, and long term goals.
Planning for Unexpected Expenses Before They Happen
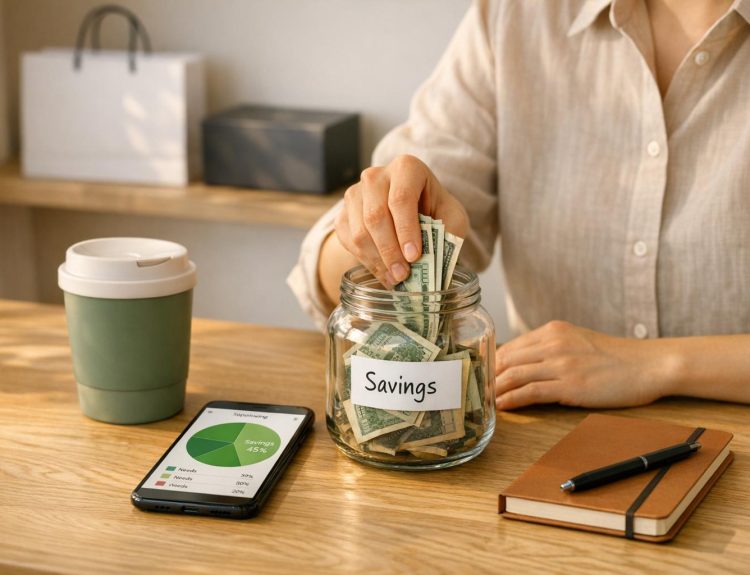
Unexpected financial demands can arise from medical appointments, vehicle repairs, household maintenance, or temporary changes in employment. Without adequate preparation, even manageable expenses can disrupt a household budget. Establishing an emergency fund creates a financial buffer that reduces dependence on borrowing during difficult circumstances.
The amount required varies according to income stability, essential expenses, and personal responsibilities. Some households may begin by saving a small amount each month before gradually building a larger reserve. Consistency is often more important than the initial contribution. Keeping emergency savings accessible and separate from everyday spending can make it easier to respond to unexpected situations without compromising other financial commitments.
Balancing Urban Lifestyle Preferences With Financial Goals
Living in a major city provides access to employment opportunities, entertainment, cultural experiences, and convenient services. However, these advantages may come with higher everyday expenses. Residents must often balance housing costs, transportation, recreation, and personal interests within a limited budget.
A Melbourne lifestyle blog may explore neighborhood experiences, local attractions, and different approaches to enjoying city life. From a financial perspective, discovering affordable activities and community resources can help residents maintain an active lifestyle without excessive spending. Visiting public parks, attending free community events, and exploring local markets can provide enjoyable experiences while supporting responsible budgeting. Financial planning becomes more sustainable when it accommodates personal enjoyment rather than focusing exclusively on restrictions.
Teaching Financial Responsibility Through Family Decisions
Financial habits often develop through everyday experiences within the household. Children observe how adults discuss purchases, manage expenses, and respond to financial challenges. These observations can influence their understanding of money long before they begin earning independently.
Discussions featured in a family blog Australia readers might follow can encourage parents to consider practical ways of introducing financial responsibility at home. Simple activities such as comparing grocery prices, setting savings goals, or discussing the difference between needs and wants can create useful learning opportunities. Involving family members in appropriate budgeting conversations also encourages shared responsibility. Financial education becomes more meaningful when connected to real situations rather than presented only as abstract advice.
Understanding the Hidden Cost of Delaying Financial Planning
Postponing financial planning is easy when immediate responsibilities seem more urgent. People may assume they can begin saving, reducing debt, or preparing for retirement once their income increases. However, delaying these decisions can limit future flexibility and make financial goals more difficult to achieve.
Starting with manageable actions can create meaningful progress. Reviewing existing debts, identifying unnecessary expenses, and establishing automatic savings contributions are practical first steps. Individuals considering investments should also evaluate their financial circumstances, risk tolerance, and time horizon before committing money. Building financial stability generally requires patience, consistent habits, and periodic adjustments rather than dramatic changes.
Conclusion
Financial well being depends on numerous decisions that extend beyond major purchases and investment choices. Everyday convenience, transportation, housing, lifestyle preferences, and family responsibilities all influence long term financial outcomes. Taking additional time to evaluate these choices can reveal opportunities to reduce unnecessary expenses while preserving the experiences that make life enjoyable. Responsible financial management is not about avoiding every indulgence or constantly worrying about money. It is about developing awareness, understanding personal priorities, and making thoughtful decisions that create greater financial flexibility. Small improvements in financial habits can gradually contribute to a more secure, balanced, and satisfying future.